Table of Contents
“Can I have this?” In front of the grocery checkout, the question comes up constantly. Allowance turns these requests into learning moments: children discover that money is limited, that they sometimes have to make choices, wait, or save, and that counting change has a real practical purpose. But you still need to know when to start, how much to give, and how to stay organized. Here are simple guidelines, inspired in particular by advice from the Banque de France, a three-jar method, and a calculator to connect it to your child's goals.
At what age should you start?
According to the financial education website of the Banque de France, children begin counting and gauging coin values and the cost of things around age 7 or 8, but you can introduce money concepts as early as age 4–5. Before actual allowance, younger kids can handle coins, play store, fill a piggy bank, and understand that items have a price.
School aligns with this timeline: currency is introduced in math starting in 1st grade (CP) with whole euro amounts, while cents are covered in 2nd grade (CE1), along with making change. Allowance then becomes a very real practice ground. Our mental math games, such as playing store, are a natural extension of this.
How much to give?
There is no ideal amount: it all depends on what the allowance needs to cover and your family budget. Start by defining together what it is meant to pay for: small treats (stickers, cards, candy), a magazine, or part of a more expensive toy? The longer the list, the higher the amount can be. Start modestly, using coins that your child can count themselves.
Advice from financial education experts highlights two key points: a fixed amount that varies with age, and a regular distribution, such as at the start of the week or month. For younger children, a weekly allowance is easier to manage: one week is a timeframe they can easily grasp. Around ages 9–10, you can switch to a monthly basis to help them learn long-term planning.
Regular allowance or tied to chores?
This is a big question for many families. Should you pay children when they set the table? Both approaches exist; here are their strengths and limitations.
| Approach | What it teaches | What to watch out for |
|---|---|---|
| Fixed and regular amount | Managing a budget, anticipating needs, saving | Clearly define what it covers |
| Amount tied to chores | The value of effort | Child might refuse to help "for free" |
| Hybrid: fixed amount + extra paid jobs | Budgeting and taking initiative | Reserve paid tasks for exceptional missions |
An often recommended solution: a fixed amount independent of daily household chores—since contributing to home life is everyone's business—and optionally a few paid special tasks during school vacations. Our article on household chores by age helps define these daily tasks.
The three-jar method
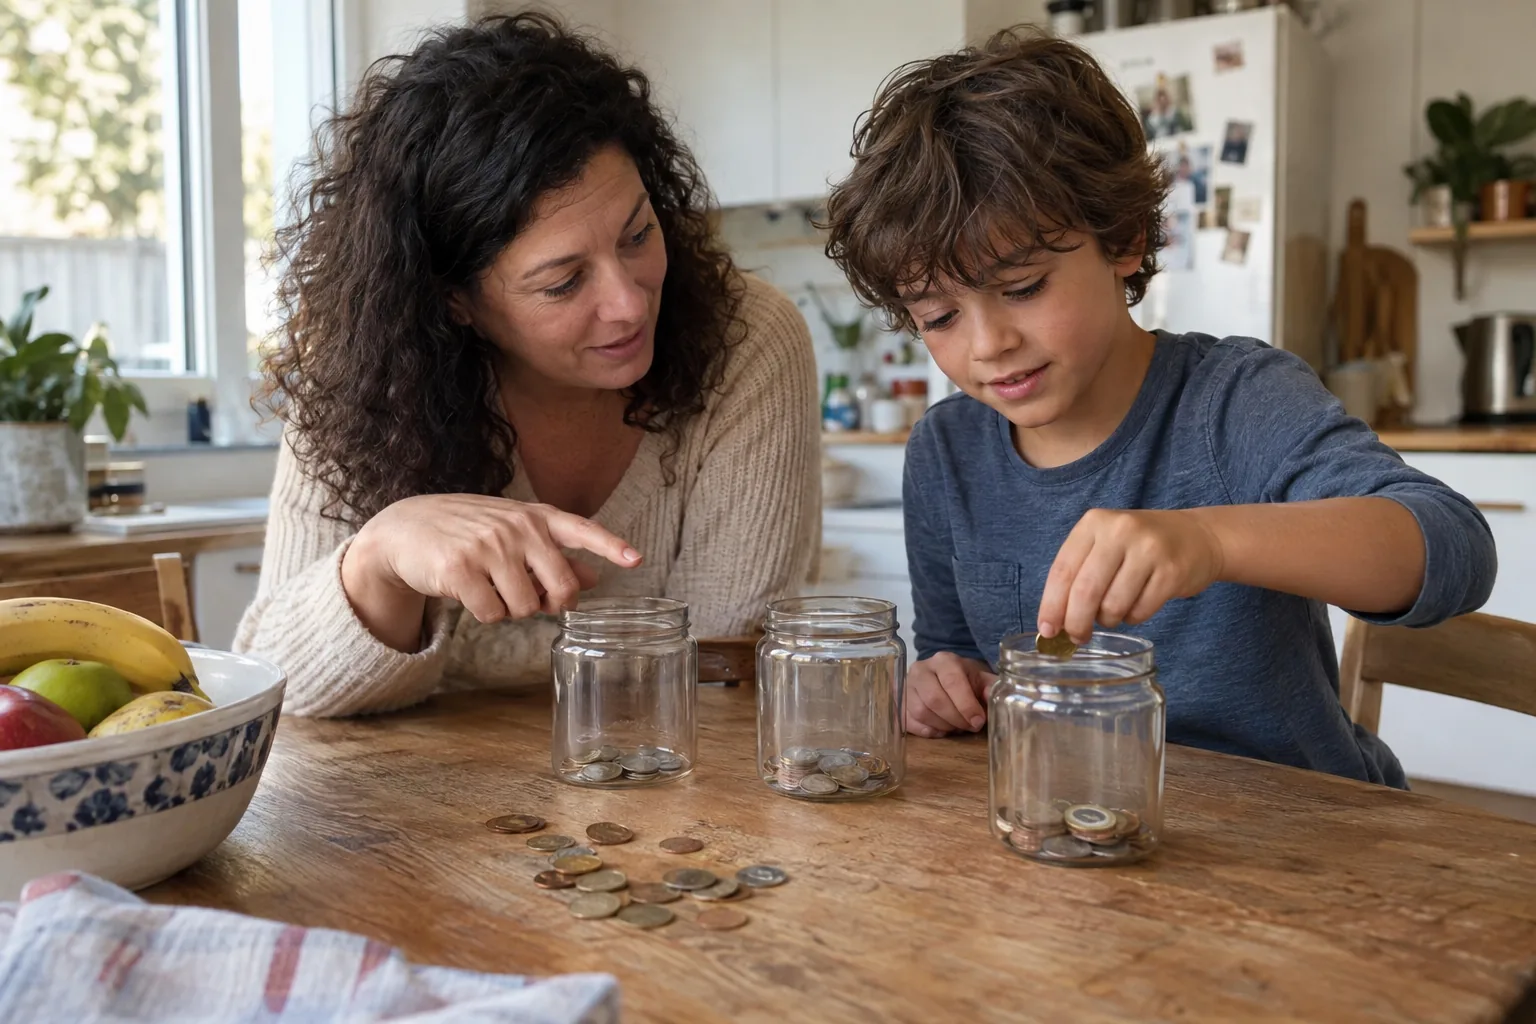
To keep allowance from vanishing in a single afternoon, many families use three clear jars: one for spending, one for saving, and one for sharing. With each payment, the child divides their coins. The "saving" jar goes toward a specific goal labeled on the lid: a book, a ball, or an outing. The "sharing" jar can fund a gift or a donation chosen by the child.
Visual feedback is essential: seeing coins stack up makes savings feel concrete. The calculator below shows how many weeks it takes to fund a project, depending on the portion set aside.
Letting them choose... and make mistakes
Allowance only teaches lessons if your child makes genuine choices. If they spend everything on day one on a toy that breaks the next morning, disappointment is part of the learning process. Avoid compensating or judging: instead, help them reflect on their experience. "What would you do differently next time?"
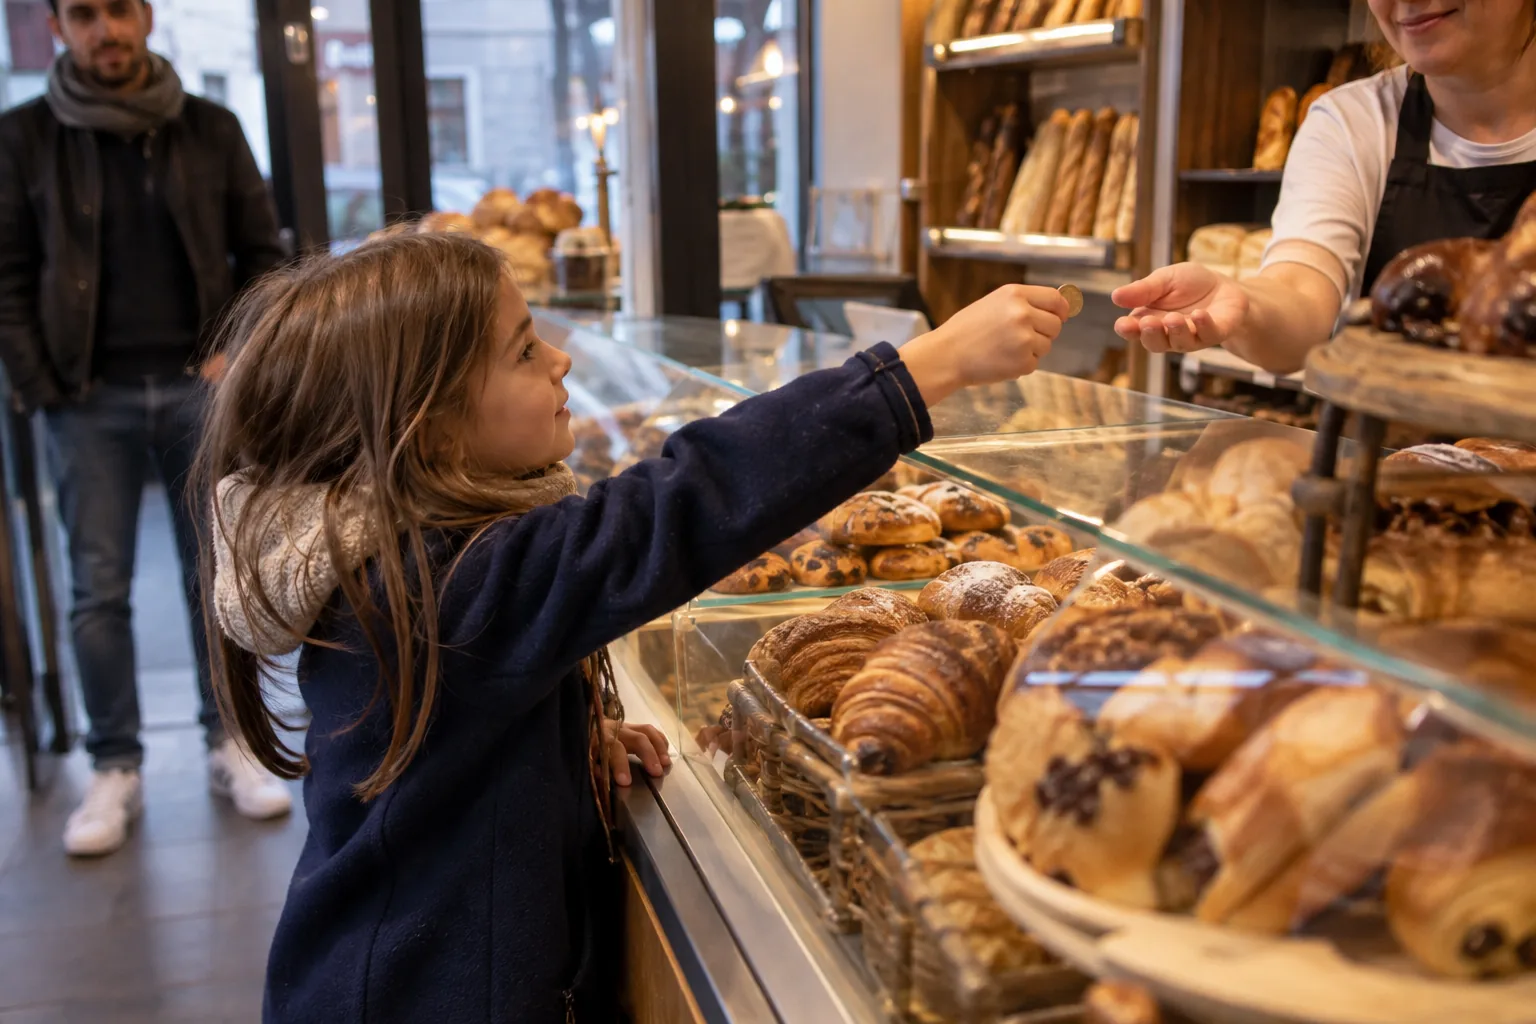
Also encourage moments of independence: paying by themselves at the bakery, counting their change, comparing prices on a shelf. Real-life situations like these are worth dozens of worksheets.
Practicing math with pocket money
Counting savings, figuring out how much is missing, checking change: pocket money offers endless math practice. From 2nd grade (CE1 equivalent, around age 7–8), you can introduce cents and price comparisons: "This item costs €2.50, and this one costs €1.80. Which one is cheaper? By how much?" These are the exact skills practiced in school, powered by real-world motivation.
A savings account: at what age?
For larger sums, such as birthday money, a savings account can be opened by parents in the child's name at any age; dedicated youth accounts are usually reserved for ages 12+. For a child under 10, handling real coins remains essential: digital money is far too abstract at this age.
Frequently asked questions
At what age should you start giving allowance?
You can introduce a child to money as early as 4–5 years old with a piggy bank and play activities. A regular allowance makes the most sense around 7–8 years old, when children can count and understand the value of coins.
Should allowance be withheld as a punishment?
It is best to avoid it. Allowance is a learning tool; if it becomes a reward or a punishment, it loses its predictability and the child can no longer learn to budget. Discipline belongs elsewhere.
What should be done with money received as a gift?
You can agree on a rule: a small portion for immediate enjoyment, and the rest for a special goal or a savings account. Discussing this with your child helps them understand the difference between spending and saving.
Should allowance pay for school supplies?
No, essential expenses remain the parents' responsibility. Allowance covers small treats and personal projects chosen by the child.
To go further
Preview before choosing
Les Grands Curieux · Ages 7–10
For children who are beginning to read instructions on their own and enjoy playing with words, numbers, and riddles. An adult can help with reading.